A Foreign Inward Remittance Certificate is a bank document confirming that foreign currency arrived in India through the banking channel. Only an Authorised Dealer Category-I bank issues one. For a stablecoin-settled payment, the certificate exists only if foreign currency actually reached an Authorised Dealer bank, which depends entirely on how the payment was routed, not on which token was used.
That single test resolves most of the confusion on this subject. The rest of this article explains the test, why it works, and what to check before your next export payment.
What is a FIRC, and does it still exist?
A Foreign Inward Remittance Certificate is issued by an Authorised Dealer Category-I bank as evidence that foreign currency was credited to an Indian account through official banking channels. Reserve Bank of India and Foreign Exchange Dealers Association guidelines restrict issuance to those banks.
The part most advice online has not caught up with. For export-related remittances settled after 20 June 2016, banks stopped issuing the physical certificate. That change came with the Export Data Processing and Monitoring System, under which banks report inward remittances electronically to the Reserve Bank of India.
So if your bank tells you it does not issue FIRCs, the bank is correct and the guide that told you to ask for one is out of date. What exporters receive today is a Foreign Inward Remittance Advice, commonly issued electronically as an e-FIRA. The physical certificate survives mainly for capital account flows such as foreign direct investment and foreign institutional investment.
Read next: paying Indian contractors
FIRC, FIRA, e-FIRC or e-BRC: which one do you need?
Four names, four documents, four different jobs. Asking for the wrong one is why these requests bounce between the exporter, the bank and the accountant for weeks.
| Document | Issued by | What it proves | When you need it |
| FIRC | Authorised Dealer Category-I bank | Foreign currency was received | Largely capital account flows today. FDI, FII, ODI returns |
| FIRA, or e-FIRA | Authorised Dealer bank, often delivered through a payment provider's dashboard | An inward foreign payment was credited against an export | The everyday proof for service exporters. Supports GST refund claims and income tax reporting |
| e-FIRC | The crediting bank, within EDPMS | Links a remittance credited at one bank to export documents held at another | Where your Authorised Dealer code sits with a different bank from the one receiving the funds |
| e-BRC | Self-certified by the exporter on the DGFT portal, against remittance data the bank reports | A specific export invoice has been realised and closed | Goods exports, and software exports filed under SOFTEX. Required for DGFT incentive schemes |
The simplest way to hold it. A FIRA proves money arrived. An e-BRC proves that money closed out a specific export. Service exporters usually need the first. Goods and SOFTEX-filed software exporters usually need both.
One update worth noting. The e-BRC format changed on 13 January 2026. DGFT's revised Appendix 2U added mandatory GST fields (GSTIN, GST invoice number and GST invoice date), plus a QR code for validation. Invoice-level mapping between GST invoices, shipping bills and inward remittances is now expected, which makes clean advice records upstream more valuable than they were.
When does an Indian exporter actually need one?
Four situations, in descending order of how often they bite.
Claiming a GST refund on exported services. Under Section 2(6) of the Integrated Goods and Services Tax Act, a supply counts as an export only when five conditions are met together, one of which is that payment was received in convertible foreign exchange, or in Indian rupees where the Reserve Bank of India permits. The advice is the evidence for that condition.
Income tax reporting. It distinguishes export revenue from a personal transfer, which matters when an assessing officer asks.
Closing entries in EDPMS. Unmatched entries sit open against the exporter and can result in caution listing.
DGFT incentive claims. Here the e-BRC rather than the advice is the operative document, and it is generated from the remittance data the bank reports.
Does a stablecoin payment produce a FIRC or e-FIRA?
It depends on the routing, and there is a single test that settles it.
The test: did foreign currency reach an Authorised Dealer Category-I bank, and did that bank file an Inward Remittance Message in EDPMS?
If yes, an advice can be issued. If no, it cannot, and no provider can manufacture one.
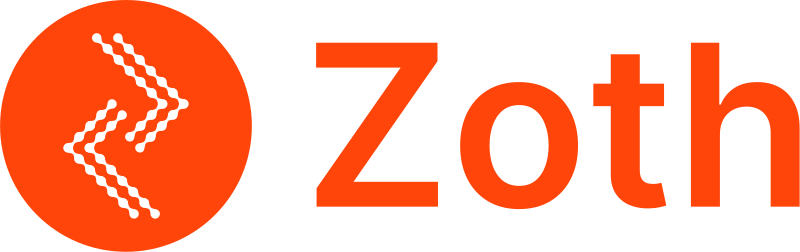
Work the chain and it becomes obvious why. Foreign currency arrives at an Authorised Dealer bank in India. The bank credits the exporter. The bank uploads an Inward Remittance Message to EDPMS. The advice is issued against that filing. Every link is required. Remove one and the document at the end of the chain does not exist.
Now apply the test to the three ways a stablecoin payment can reach an Indian exporter.
| Routing | Does foreign currency reach an AD bank? | Advice available? |
| Client sends USDC or USDT to the exporter's wallet, exporter sells on an Indian exchange | No. Nothing entered through the banking channel | No |
| Client converts to dollars, then instructs a wire to the exporter's bank | Yes | Yes |
| Client funds a payout platform in stablecoins, platform routes the payment into India | Depends on the platform's structure. See below | Ask the platform |
Why a payment to your wallet cannot produce one
Two reasons, and both are structural rather than procedural.
No Authorised Dealer bank was involved. A token moving to a wallet does not touch the banking channel. There is no credit for a bank to certify and no Inward Remittance Message to file. The chain never starts.
The receipt is not foreign exchange. Under Section 2(47A) of the Income Tax Act, USDC and USDT are Virtual Digital Assets. They are not foreign currency. When the exporter sells the token on a domestic exchange, what they receive is the proceeds of a domestic sale, not an inward payment from abroad.
The consequence runs further than a missing document. Condition four of the export test under Section 2(6) is not satisfied, which means the supply may not qualify as an export at all, and with it go the zero-rated treatment and the input tax credit refund.
What about payments converted outside India and credited in rupees?
For payments converted outside India and credited in rupees, eligibility depends on whether foreign currency enters India through an Authorised Dealer bank before the rupee credit.
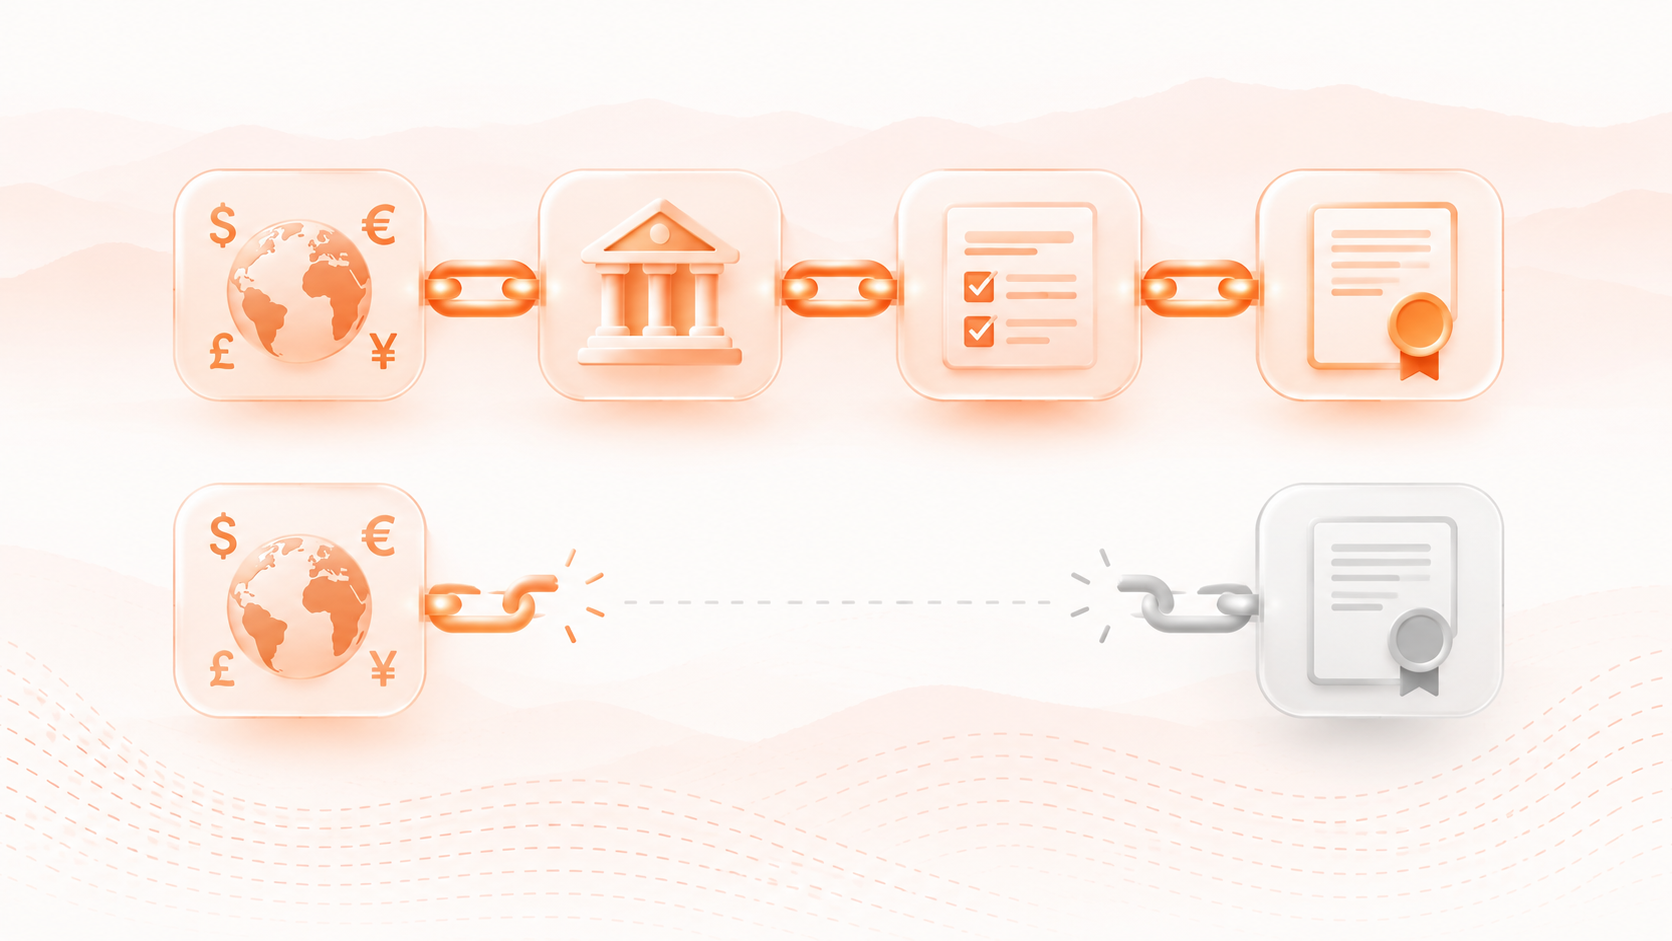
Where a platform converts stablecoins to foreign currency offshore and that foreign currency lands in a collection account at an Authorised Dealer bank in India before being converted and credited to the exporter in rupees, the chain is intact. Foreign currency reached an Authorised Dealer bank. The Inward Remittance Message can be filed. The advice can be issued. This is the same structure that lets receipts through established international payment platforms qualify.
Where only rupees cross the border, the position is different and depends on whether that particular rupee route is one the Reserve Bank of India permits. The Central Board of Indirect Taxes and Customs has clarified that rupee receipts from Special Rupee Vostro Accounts satisfy condition four, which indicates how narrowly the permitted rupee routes are defined.
The rule to carry away. The settlement technology does not decide eligibility. The proof document does, and the proof document depends on whether an Authorised Dealer bank sat in the chain. Ask any provider that question directly, and expect an answer that names a bank.
There is also an authorisation layer. Non-bank entities facilitating cross-border payments for the import and export of goods and services fall under the Reserve Bank of India's Payment Aggregator Cross Border framework, introduced by circular on 31 October 2023, which replaced the earlier online payment gateway service provider arrangements. Non-bank providers require authorisation as a payment system operator, with prior registration with the Financial Intelligence Unit India. Authorised Dealer Category-I banks do not need separate authorisation.
How do you get an e-FIRA?
Where the payment came through a bank, five steps.
One. Request the advice from the bank that received the credit, or download it from your payment provider's dashboard where the provider makes the bank's advice available.
Two. Supply the transaction reference, the date, the amount, the sender's name and the invoice it relates to.
Three. The bank verifies the details and files the Inward Remittance Message in EDPMS.
Four. The advice is issued, usually by email or through the bank's portal.
Five. Where your Authorised Dealer code sits with a different bank from the one that received the funds, the crediting bank issues an e-FIRC and the Authorised Dealer bank completes the EDPMS filing. This is the situation e-FIRC exists to handle.
Traditional bank requests typically take one to two weeks and carry a per-document fee. Providers that deliver the bank's advice through a dashboard remove that step.
What if the GST department asks for a FIRC and your bank does not issue one?
A common and frustrating position, and it has an answer.
The refund provisions require proof that payment was received in convertible foreign exchange. They do not prescribe a FIRC by name. Since banks no longer issue physical FIRCs for export remittances settled after June 2016, insisting on one asks for a document that cannot be produced.
The practical response is to submit the e-FIRA or the e-BRC together with a bank confirmation, and to reference the Reserve Bank of India circulars that moved export reporting to EDPMS. Where the claim is still rejected, the grievance and appeal routes remain open.
The wider lesson is worth stating: keep the documentation trail clean at the point of receipt rather than assembling it at claim time.
Where the trail usually breaks
Four failure points, all avoidable.
The purpose code is wrong. The purpose code classifies the receipt under FEMA reporting. An incorrect code creates a mismatch that surfaces during a refund claim.
The Authorised Dealer code does not match the receiving bank. Where the code registered with customs sits with a different bank from the one receiving funds, the payment may show as unrealised in EDPMS even though the money has arrived. Correcting it means coordinating between two banks.
The amount does not reconcile to the invoice. Netted fees, rounding and partial payments break the link between the receipt and the invoice it is supposed to close.
Realisation runs past the window. Export proceeds must be realised within the period the Reserve Bank of India permits, extended to fifteen months from the date of export under the November 2025 amendment. Under Rule 96A of the CGST Rules, where proceeds are not realised in time, the exporter must pay the integrated tax not charged, with interest, and recover it once payment arrives. The consolidated Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 took effect on 1 October 2026 and revised these provisions.
What to check before your next export payment
Five things, and they take a few minutes each.
- Confirm which document your claim actually requires. Services usually need the advice; goods and SOFTEX-filed software need the e-BRC.
- Ask your provider which bank issues the advice and against what receipt. If the answer is that the platform issues it, look harder.
- Check the purpose code applied to your receipts.
- Verify your Authorised Dealer code is registered correctly against the bank actually receiving your funds.
- Reconcile receipts to invoices monthly rather than at claim time.
Running payouts across emerging markets? Audit your cross-border payout fees with zPayments today.
Regulatory Disclosures & Mandatory Risk Notices
Disclaimer: This article is provided for informational and educational purposes only and does not constitute financial, legal, tax or investment advice.
Service Availability & Compliance: Zoth Payments Limited is registered with FINTRAC as a money services business. Local-currency payouts are delivered through regulated payout partners, subject to applicable local laws. All transactions remain subject to identity verification (KYC/KYB), anti-money laundering (AML) monitoring, sanctions screening and the FATF Travel Rule. Submission of a payout does not guarantee its execution or timing, and exchange rates, payout amounts, fees and settlement times may vary.
Digital Asset Risk Notice: Stablecoins and digital assets carry inherent risks, including market volatility, potential de-pegging, smart contract vulnerabilities, liquidity limitations and changing regulatory frameworks. Digital assets are not legal tender in most jurisdictions and may not be backed by government deposit insurance (e.g., FDIC, CDIC).